Jonathan Doughty is a global thought leader, consultant, speaker, moderator and C-suite executive in the foodservice and leisure sectors working around the world in retail, transit and leisure. In this column, he talks about the changes in the industry in the last quarter of a century.
Twenty-five years ago, food in many shopping centres largely served the shopping trip: somewhere to refuel, occupy children or pause between purchases. Today, food increasingly provides the reason to visit. Restaurants, cafés and food halls help centres compete for people’s leisure time, alongside their retail spending.
This evolution has been uneven. Nevertheless, five significant changes have reshaped the sector, with implications for its next chapter and for all of us involved in it.
1. Choice has become richer, broader and more distinctive
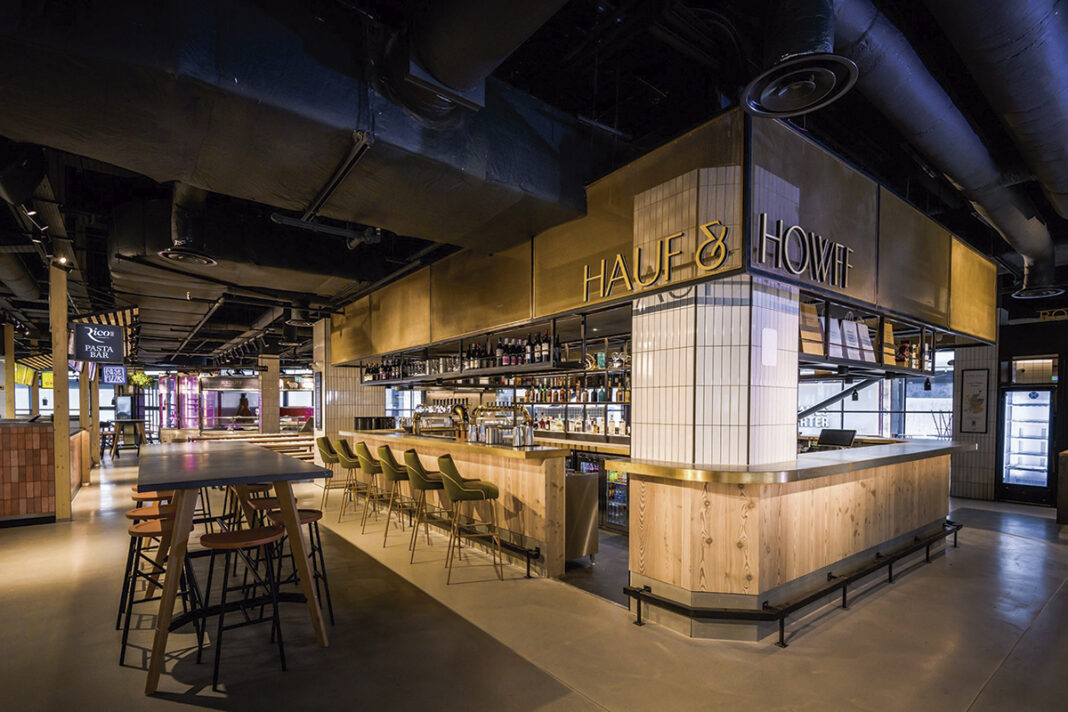
The familiar food court remains valuable but now sits within a wider culinary landscape. Quick meals share space with specialist coffee, regional cooking, premium restaurants and food experiences that combine eating, shopping and discovery, all making up the culinary landscape of shopping.
At Bangkok’s ICONSIAM, SOOKSIAM celebrates food and traditions from Thailand’s 77 provinces, including permanent and rotating operators. It demonstrates that diversity can mean exploring local culture as much as importing international brands.
Looking forward meaningful choice will depend on differences in price, occasion, dietary needs and cultural identity. Twenty restaurants offering similar experiences do not necessarily create diversity. The strongest destinations will balance discovery with everyday affordability.
2. Emerging Brands Have More Ways In
Shopping-centre dining was often associated with established chains able to fund substantial fit-outs and long commitments. Food halls, kiosks and pop-ups have widened the routes available to smaller businesses and landlords have dedicated food teams now that know their business – food.
Bonnie & Wild, within Edinburgh’s St James Quarter, brings together independent, chef-led operators. Its Breakfast Club pop-up was explicitly presented as one of several start-ups gaining their first foothold in the food hall.
Smaller formats and shared seating can reduce some entry barriers, although access does not guarantee profitability. The next step is commercial flexibility: manageable occupation costs, practical operational support and opportunities to grow. Independent operators need a business model that allows independents to survive. We have all learned this over the last 25 years with both success and failure.
3. Food has extended the trading day
The lunchtime peak has developed into a sequence of occasions: breakfast, morning coffee, lunch, afternoon treats, dinner and later socialising. Different customers can use the same destination for different reasons throughout the day. “Day parts” is in our common language finally.
Eataly in London illustrates this breadth, opening daily from 7.00am and serving food into the late evening. The opportunity is to build repeat visits around daily routines, rather than relying entirely on shopping frequency. Food to go, food to buy, food to eat now all in one magical space.
Culture shapes these rhythms, too: working patterns, school schedules, customary mealtimes and religious observance should inform the offer. Future planning must start with local behaviour, then match staffing, menus and access accordingly.
4. Food and leisure have become deliberately connected
A cinema beside a food court is hardly new. The stronger change is the creation of coordinated destinations where eating, entertainment and social space reinforce one another.
Melbourne’s Chadstone makes this explicit through The Social Quarter, combining restaurants and a brewery with bowling, mini golf and immersive games. Customers can build an outing around several activities, with food linking the experience. We have learned that “old places” have a magic and an aura that just makes them “better” than new builds, helping to preserve some stunning, but unused infrastructure in our cities and towns.
Climate is central to making these places work. An exposed terrace needs shade in heat, shelter in rain and protection from wind. In colder climates, comfortable indoor connections matter; in tropical conditions, cooling and rain protection can determine whether people linger.
5. Centres can support a genuine night-time economy
Evening dining has increasingly become a destination business with its own audience and operational needs. Dubai Mall, for example, lists restaurant and food-court hours extending to midnight on weekdays and 1am from Friday to Sunday. Climate and culture have a lot to do with this, but knowing you can, means you will and you only need to watch the steady stream of taxis dropping off tourists from all over Dubai in the evening for the shopping, dining and “show”.
This example proves one thing. A night-time economy need not revolve around alcohol. Family meals, desserts, coffee and entertainment can be equally important. Gulf summer heat strengthens the appeal of comfortable indoor environments, while Ramadan creates distinctive rhythms around iftar and suhoor.
Making this work requires safe arrival and departure, clear access after shops close, coordinated opening hours and reasons to stay. Gastronomy earns its place when it connects commercial ambition with the way people actually live.
25 years on from the start of the millennium we are all still learning – which is a good thing and something I still have an appetite for.